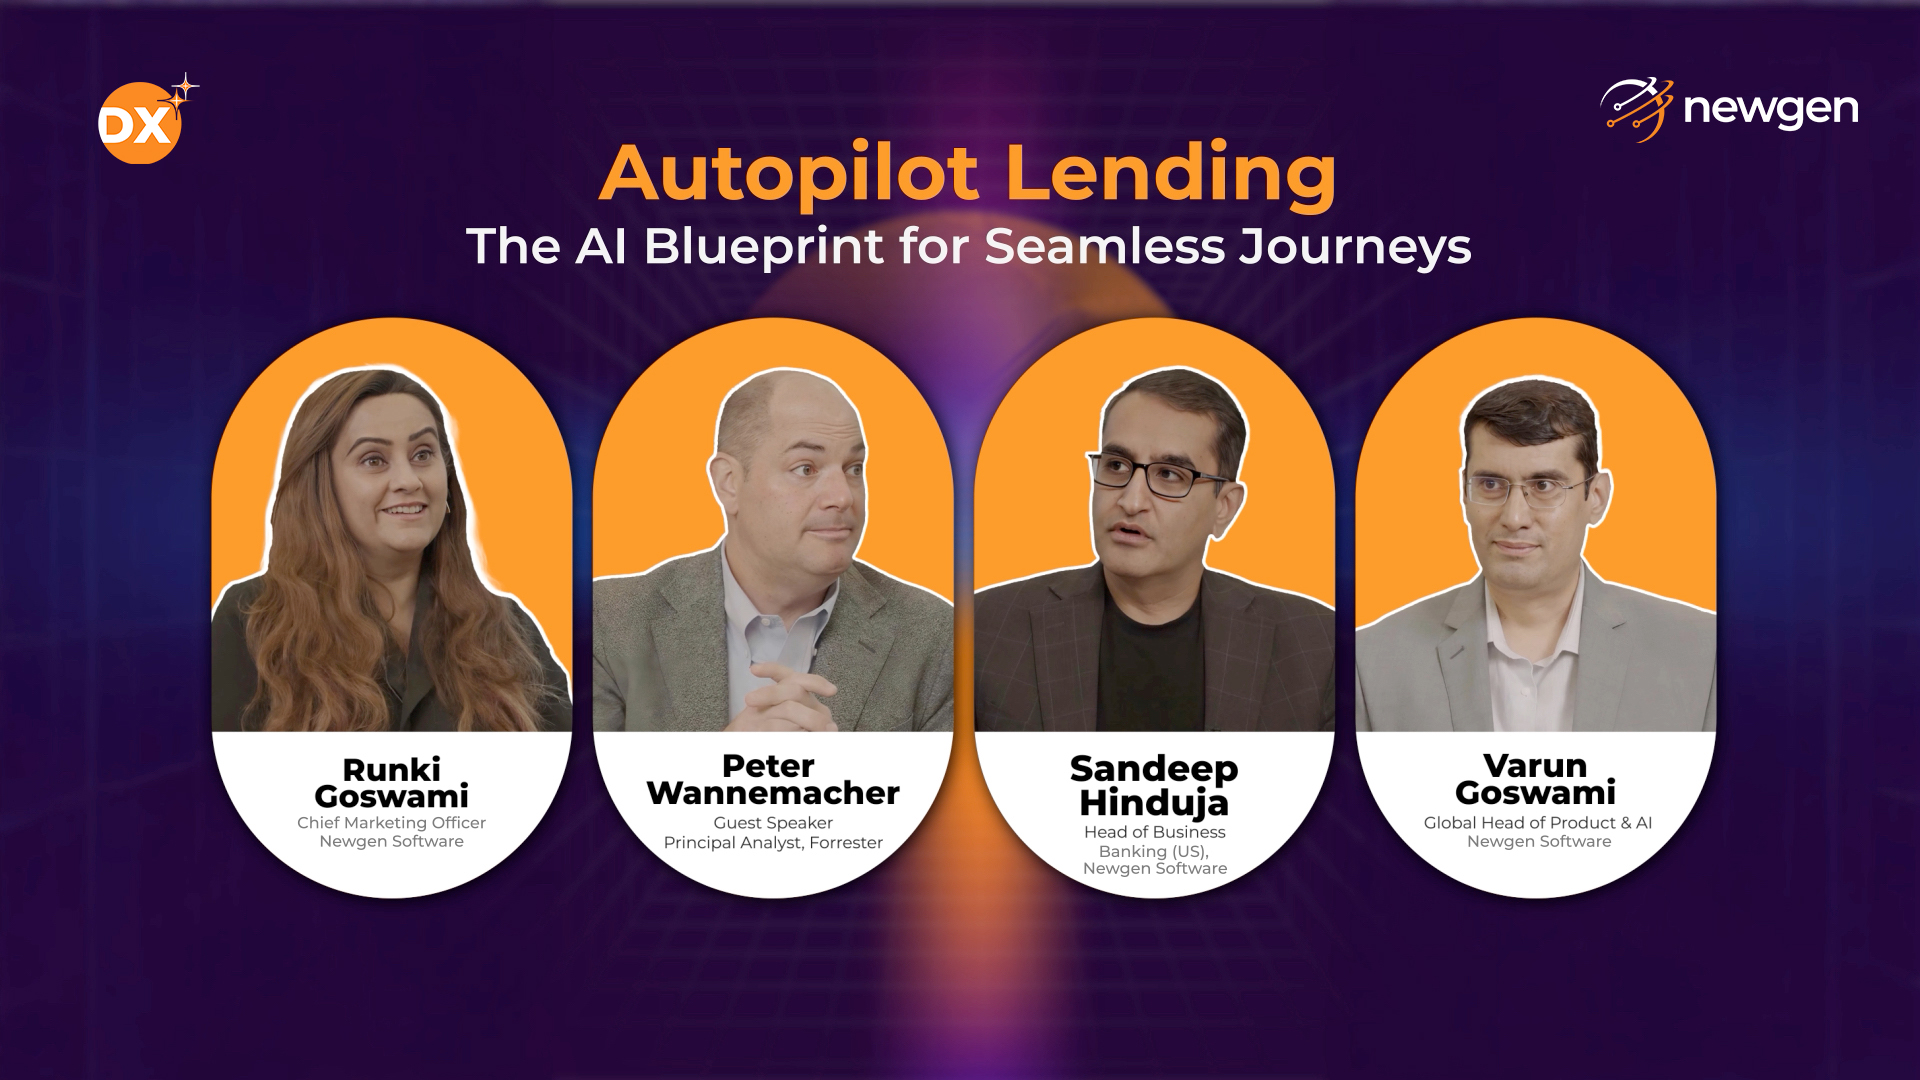
In a recent DX++ conversation on Autopilot Lending, industry leaders examined why many AI in lending initiatives deliver efficiency but fall short of structural transformation. Loan timelines have compressed significantly. In unsecured segments, decisions that once required days are now completed in minutes. From the outside, AI in digital lending appears mature.
Beneath that acceleration, however, operational friction remains.
Borrowers still upload the same documents multiple times. Backend teams reconcile data across disconnected systems. Compliance checks surface late in the journey. What appears streamlined externally often reflects internal fragmentation.
The Structural Constraint Behind AI in Lending
Most lending ecosystems evolved incrementally rather than through intentional orchestration. Application intake spans multiple channels. Underwriting systems operate independently. Disbursement engines and servicing platforms function separately. Data governance frameworks reflect historical growth rather than unified design. When institutions introduce AI into loan origination or credit underwriting within a single segment of this stack, they improve that segment. The surrounding silos remain intact. Acceleration layered onto fragmentation does not create transformation. It shifts inefficiencies from one stage to another. This explains why many AI initiatives in commercial lending and consumer lending stall after initial success. Automation improves throughput, but it does not unify the journey.
From AI-Led Enhancements to AI-First Architecture
A key distinction discussed during Autopilot Lending was the difference between AI-led initiatives and AI-first platforms. In an AI-led model, intelligence is introduced as an enhancement. A machine learning model refines credit scoring. A tool accelerates document ingestion. A workflow shortens underwriting review cycles. In an AI-first model, artificial intelligence in lending is embedded into the operating architecture. Intelligence becomes foundational rather than additive. AI-first lending platforms integrate intelligent document processing, real-time credit decisioning, business rule management, risk modeling, workflow orchestration, and compliance validation into a unified system. This structural integration enables agentic AI in lending systems. Agentic AI differs from conventional automation because it operates with contextual awareness. Intelligent agents can access borrower data, interpret institutional policies, execute predictive models, and provide decision support within defined governance guardrails. Instead of completing isolated tasks, they support knowledge workers across the lending lifecycle. Without this integration, AI remains isolated. It improves individual processes but does not redefine how lending operates.
The Pilot Trap and the Governance Imperative
Pilot fatigue remains a persistent challenge across AI in lending initiatives. Institutions test machine learning models for risk scoring. Generative AI improves document processing. Decision engines enhance underwriting support. Technically, many pilots succeed. Operationally, scaling proves difficult. The barrier is rarely model performance. It is scalability, clarity of return on investment, auditability, and regulatory alignment.
In highly regulated environments, particularly within artificial intelligence in banking and finance, explainability is essential. Risk teams require transparency. Regulators demand traceable decision-making. Leadership expects measurable commercial outcomes. Without unified data governance and enterprise orchestration, even advanced AI in lending decisions remains confined to proof-of-concept. Scale must be designed into the system from the outset. Governance is not an afterthought. It is a structural requirement.
Measurable Impact of Structural Redesign
The impact of architectural redesign is measurable. As shared during the discussion, a US retail bank transitioned personal and auto loan origination onto an AI-first lending platform. Before the transformation, unsecured loans required three to five days and relied heavily on manual review.
After implementing intelligent document processing, automated KYC validation, and real-time credit decisioning, approval times decreased by 75%. Loan booking rates increased by 21%. Overall loan volume rose by 18%, while operational costs declined by 32%.
These results were not driven by isolated automation. They were achieved through end-to-end orchestration across the lending journey. For institutions evaluating AI in lending, the starting point is organizational readiness rather than tool selection. Leaders must assess where enterprise data resides, how fragmented underwriting and servicing systems are, where manual interventions persist, and whether infrastructure can scale AI workloads responsibly. Transformation must address people, processes, and technology together. Adoption planning and change management are as critical as algorithm performance. A disciplined approach begins with one defined lending
journey, whether personal loans, SME lending, or mortgages, and reimagines it end-to-end. Narrow automation initiatives may deliver incremental gains. Structural redesign creates durable competitive advantages.
Autopilot lending goes beyond accelerated decision-making. It reflects a broader shift in how financial institutions balance borrower expectations, regulatory scrutiny, and profitability. Borrowers seek certainty and simplicity. Regulators require resilience and explainability. Lenders demand growth without disproportionate risk exposure. AI in lending sits at the intersection of these demands. Institutions that treat artificial intelligence as an enhancement will achieve incremental efficiency. Those who redesign their architecture for intelligence will define the next phase of lending transformation. In lending, intelligence without orchestration is incremental. Architecture is what makes it transformative.